Webinar: Before and After the Event
California SaaS Sales Tax in 2027: What Changes Under SB 122?
A practical look at what to do before January 1, for companies that sell software and companies that buy it.
Live webinar | Thursday, October 29 | 11:00 a.m. Pacific | 60 minutes | No cost
SB 122 brings electronically downloaded and remotely accessed software, and certain digital products, into California’s sales tax base on January 1, 2027. This hour covers what becomes taxable, why it lands on the companies buying software as hard as on the ones selling it, and what to work through before the end of the year.
Both Sides of the Transaction
Almost everything written about SB 122 so far speaks to software companies. It lands just as hard on the other side. A company spending tens of millions a year on software licenses will likely face a significant new sales or use tax cost, depending on place of use.
If you sell software, you need to know what becomes taxable, what to do about transactions that span the January 1, 2027 operative date, and what to tell customers before they are surprised by an invoice.
If you buy software, you need to know which of your purchases become taxable, how the new sourcing and place of use rules apply to them, and what documentation supports an exemption or an allocation. There is also a five million dollar purchaser threshold that can require a company to obtain a use tax direct payment permit and self assess the tax, which is worth checking before January.
The session covers both.
On the Agenda
- The sales and purchases of prewritten computer software that become taxable under SB 122, including licenses, subscriptions, and software transferred electronically or accessed remotely.
- The products and services that remain exempt, including custom computer software, specified digital content and digital infrastructure, qualifying human effort services, reproduction rights, and software purchased solely for qualifying out of state use.
- The CDTFA guidance, what has come out so far, what questions remain open, and what is still expected.
- Steps for sellers before December 31, including product mapping, customer address. records, exemption documentation, contracts and billing systems, and transactions that span the January 1, 2027 operative date.
- Questions buyers should be putting to their vendors now.
- The direction other states are taking, with Colorado first in line.
Fifteen minutes at the end for questions, with all four on the call.
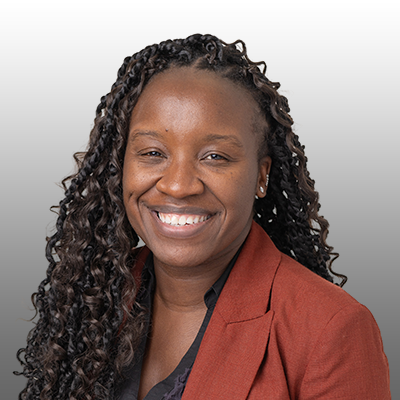
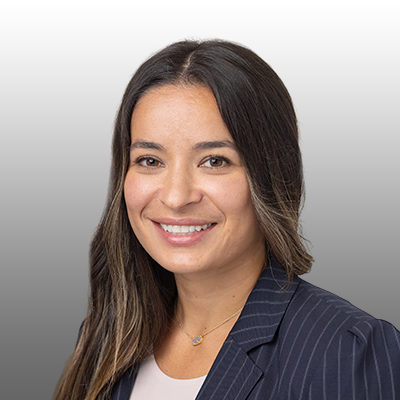
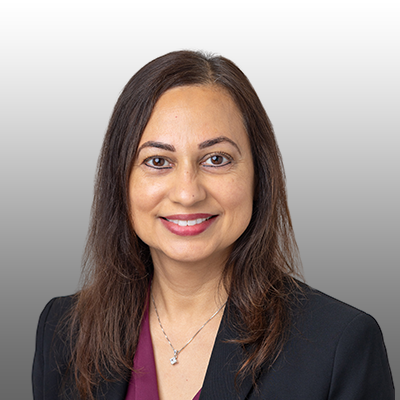
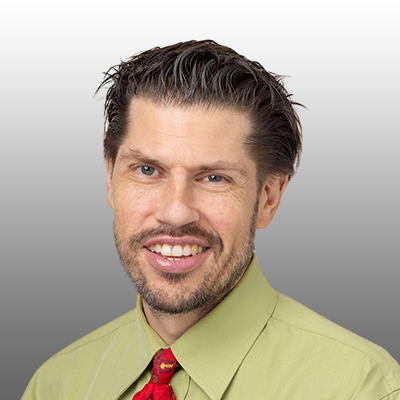
The Presenters
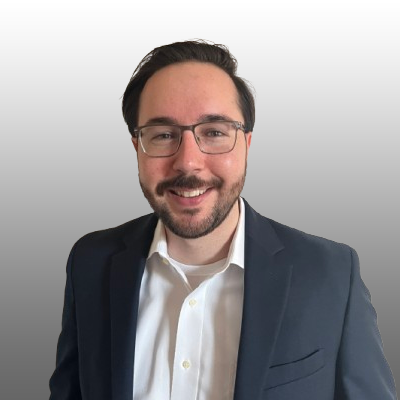
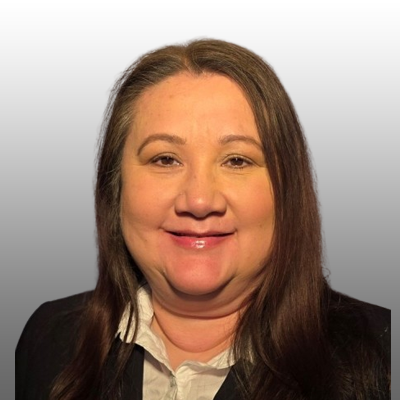
Monika Miles, President and Founder. Monika has more than 30 years of experience in multistate tax consulting, covering sales tax, income and franchise tax, and credits and incentives. She is a CPA and practiced at a Big Four firm before the firm was founded in 2002, serving clients across technology, manufacturing, retail, construction, and financial services.
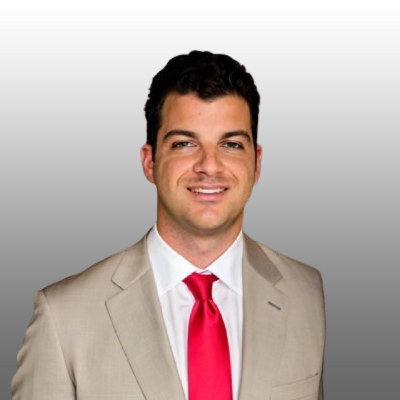
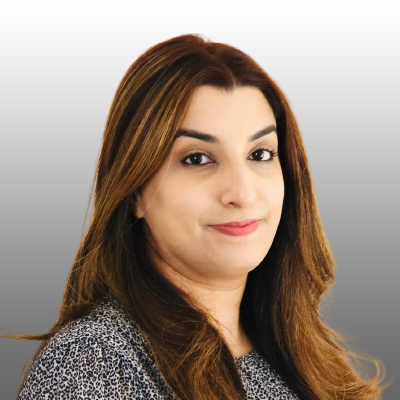
Bill Loew, Executive Vice President. Bill has more than 35 years of sales and use tax experience, including time with the California Department of Tax and Fee Administration, formerly the State Board of Equalization, and as a partner with two multinational firms. He is a CPA and a past speaker for the Institute for Professionals in Taxation.
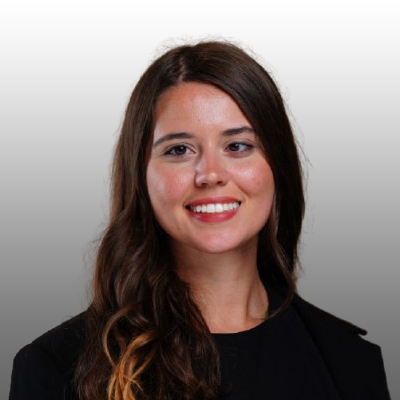
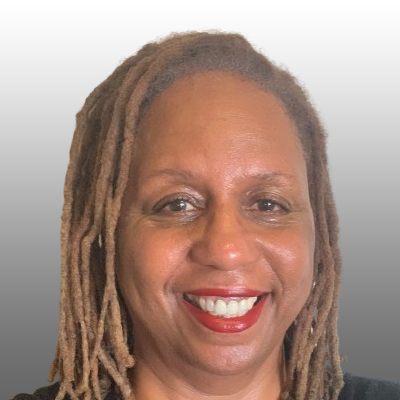
Aly Davidian, Senior Tax Manager. Aly has over 10 years of experience in sales and use tax, beginning as a California local tax specialist and continuing through six years at a Big Four firm advising on nexus, taxability, exposure, and remediation. She is a Certified Member of the Institute for Sales and Use Tax, with particular depth in retail, manufacturing, and technology.
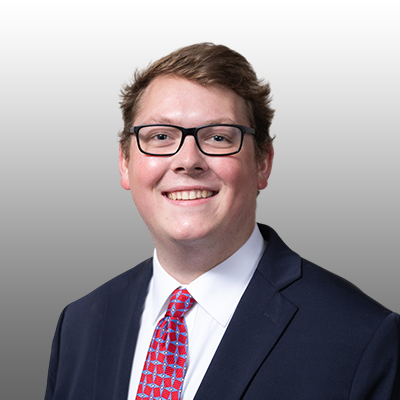
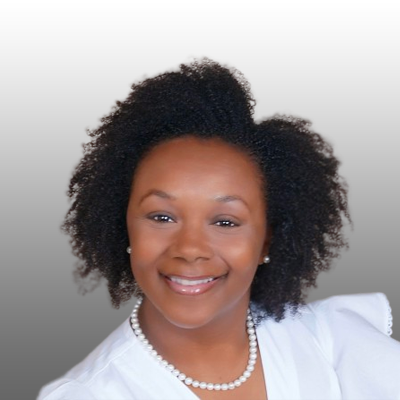
Mitch Bailey, Senior Tax Manager. Mitch has practiced public accounting since 2017, most recently in the state and local tax group at a top 10 CPA firm, where he focused on multistate sales and use tax, much of it with SaaS companies. He is a CPA in both California and Washington and works primarily with clients in the technology sector.
If You Cannot Attend Live
Register anyway. We send the recording and the slides to everyone on the list within two days, whether you made it or not.